Source: MARKET MINDS ADVISORY INSIGHTS PRIVATE LIMITED
Warehouse Robotics Market: A Building-Shaped Commitment With A Twenty-Year Payback
The robotics race is moving beyond the robot itself. AI orchestration, fleet intelligence and flexible automation are becoming the new sources of warehouse advantage.
Wilmington, DE, United States, Sept. 08, 2026 (GLOBE NEWSWIRE) -- Warehouse Robotics Market is Rapidly Becoming the New Operating Standard for Modern Fulfilment
Warehouse Robotics Market has moved past the proof-of-concept phase that dominated industry conversations for most of the last decade. It now sits at the center of how serious operators are reconstructing fulfillment economics, and a meaningful share of supply chain leaders have not yet adjusted their capital plans to reflect what the leading operators have already committed to.
What looks externally like a market still maturing is, structurally, a market in which floor space, integration capacity, and qualified deployment partners are being claimed in advance. Operators treating automation as a future capability are negotiating against operators treating it as present-tense infrastructure, and the operational gap between those two postures is widening with every fulfillment cycle.
Request a Free Sample Report: https://marketmindsadvisory.com/request-sample/?report_id=46
Key Takeaways from Warehouse Robotics Market
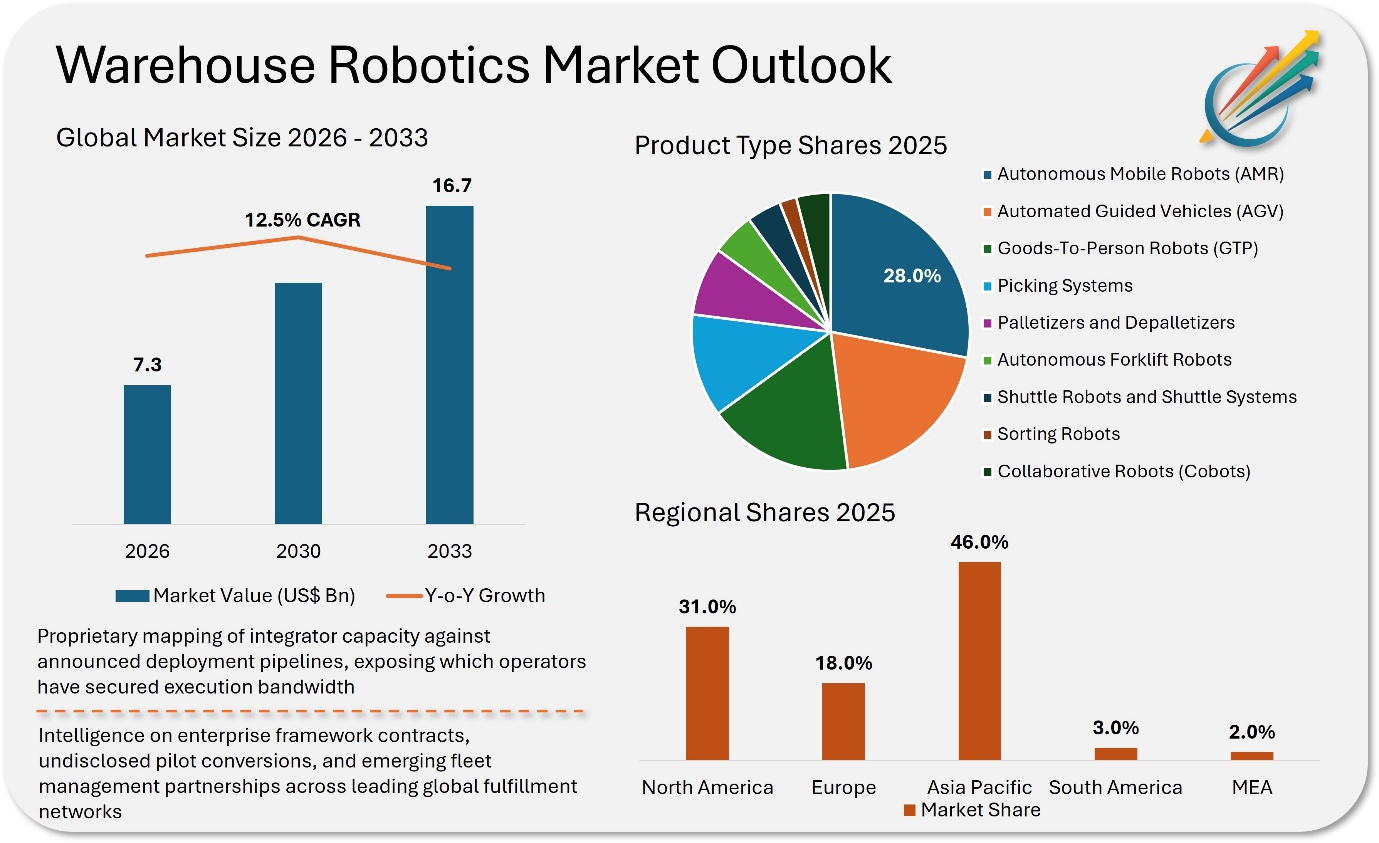
- Global warehouse robotics market valued at US$ 7.3 billion in 2026 and projected to reach US$ 16.7 billion by 2033 witnessing a CAGR of 12.5%
- Autonomous Mobile Robots accounts for the largest share of new deployment budgets
- E-commerce and third-party logistics together drive over half of demand in the warehouse robotics market
- Labor scarcity has shifted automation from to continuity strategy
- Asia-Pacific manufacturing base is reshaping global supplier economics
- Software and orchestration layers are capturing disproportionate margin in the warehouse robotics market
According to Lead Analyst from Market Minds Advisory, " Warehouse robotics market has stopped being a discretionary efficiency investment and become a precondition for operating at competitive throughput. The operators securing integration capacity and software partnerships through 2027 will set the cost structure their competitors then have to chase for a decade."
A Narrow Strategic Window is Emerging for Operators Still Evaluating Automation
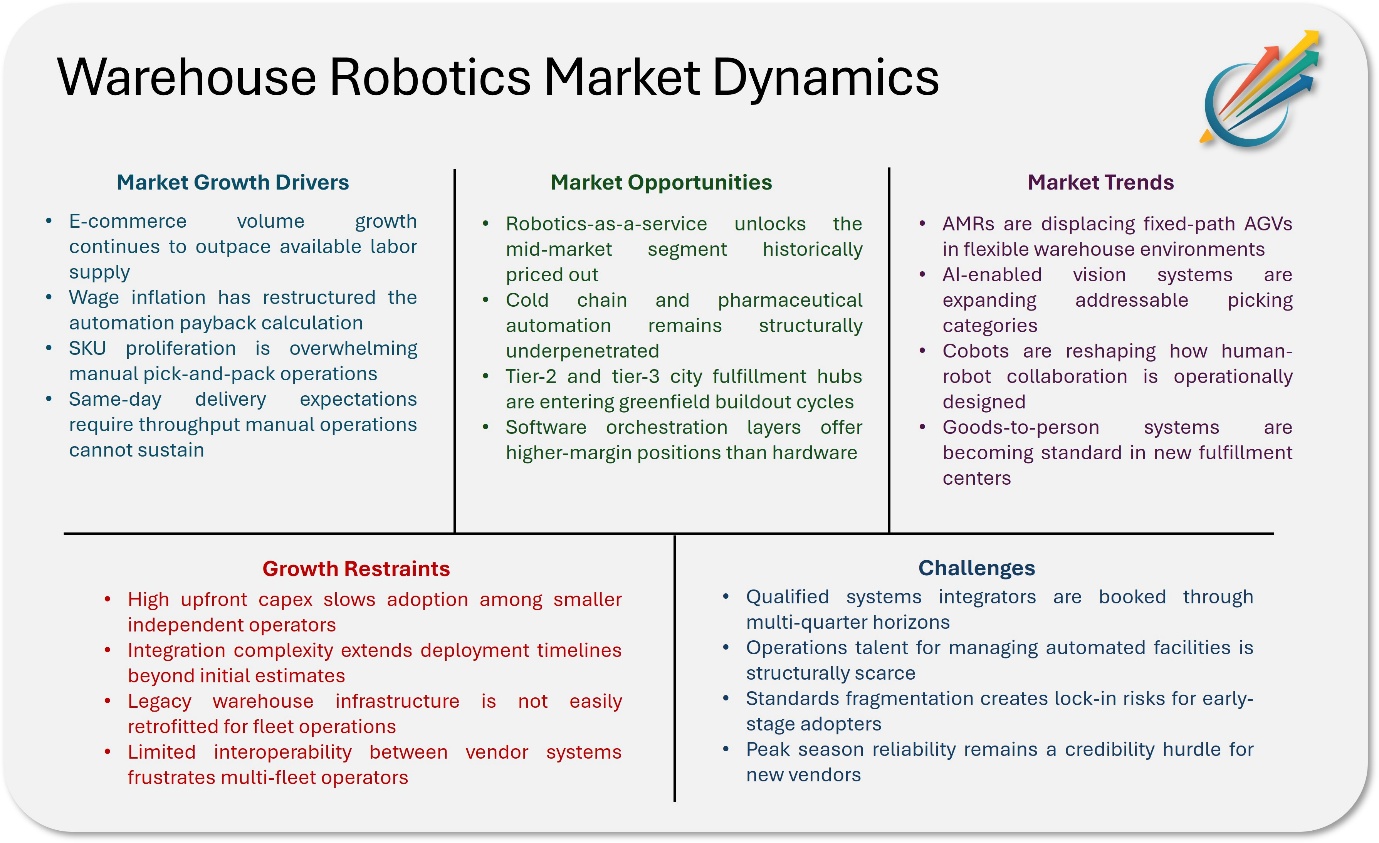
The binding constraint is no longer robot availability. It is integrator bandwidth, warehouse readiness, and access to operators who have actually run automated fleets at scale.
- Integration capacity is the real bottleneck: Hardware lead times have compressed, but qualified systems integrators are booked deep into 2027. Operators without locked engagements are quietly slipping behind.
- Software orchestration is becoming the differentiator: Fleet management, warehouse execution, and AI-driven slotting now drive more deployment value than the mechanical hardware itself.
- Lease-and-operate models are reshaping access: Robotics-as-a-service is pulling mid-market operators into automation faster than capex-based forecasts anticipated in the warehouse robotics market.
The Economics of Warehousing are no Longer Being Defined by Labor Alone
The structural shift is not fast picking, it is that the labor model around which warehouses were designed for forty years no longer reliably exists in the geographies where fulfillment volume is highest.
- Labor scarcity has become structural: Wage inflation, attrition, and seasonal staffing gaps now make manual-only operations economically unstable, not merely suboptimal.
- Warehouse design is being redrawn: New facilities are being engineered around robot fleets from day one, with aisle widths, racking heights, and dock layouts optimized for machine operation.
- The throughput ceiling has moved: Automated facilities are achieving units-per-hour rates that manual operations cannot match even with full staffing, changing what competitive parity looks like.
High-Impact Market Shifts are Missing from Mainstream Expectations
A significant share of announced automation pilots will not convert to scaled deployment by 2028. The bottleneck is not technology or capital. It is the scarcity of operations leaders who have managed mixed human-robot environments through full peak cycles. That experience is the actual scarce input.
Cobots and AMRs will cannibalize traditional AGV demand faster than vendor roadmaps suggest. Fixed-path automation is becoming structurally disadvantaged in markets where SKU velocity and layout flexibility matter more than peak throughput optimization.
The most valuable position in the value chain is shifting to the orchestration software layer. Hardware margins are compressing as Asian manufacturers scale. The companies controlling fleet management, multi-vendor coordination, and warehouse execution systems will capture disproportionate economics through 2033.
New Layer of Competitive Advantage is Emerging Across the Robotics Value Chain Convergence of warehouse execution and robot orchestration
The historical separation between WMS, WES, and fleet management software is dissolving. Operators are rejecting multi-vendor stacks that require custom integration for every new robot type. Vendors offering unified orchestration across heterogeneous fleets are winning enterprise accounts that previously defaulted to incumbent material handling suppliers, and that shift is restructuring the competitive map upstream.
AI-driven perception and adaptive picking
Computer vision and machine learning have crossed the threshold where mixed-SKU picking is commercially viable at scale. This unlocks categories like apparel, general merchandise, and pharmaceuticals that resisted automation under earlier technology generations. The vendors that built proprietary training datasets during the pilot decade are now operating with compounding advantages competitors cannot easily replicate.
Vertical integration by hyperscale operators
The largest e-commerce and 3PL operators are increasingly developing in-house robotics capability or acquiring it. This reshapes addressable market dynamics for independent vendors and creates a bifurcated landscape where hyperscale buyers internalize while mid-market operators lean harder on external integrators and as-a-service models for access to comparable capability.
Manufacturing relocation and nearshoring tailwinds
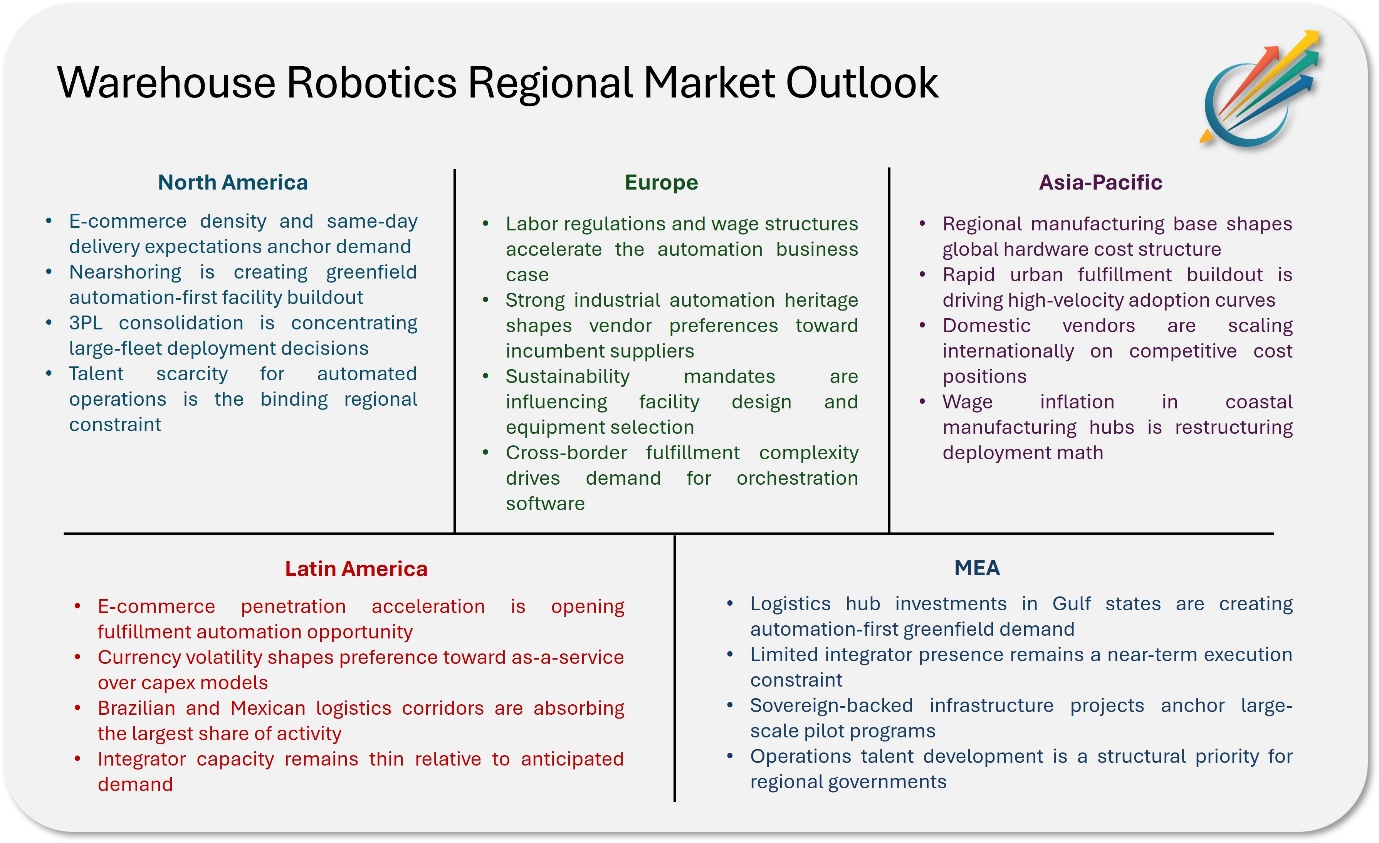
Reshoring and regional manufacturing buildout is creating greenfield warehouse demand in geographies where labor scarcity is most acute. New facilities in North America and Europe are being designed automation-first, while Asian manufacturing hubs are upgrading existing operations to defend cost positions against rising regional wages.
Risk Assessment Material Headwinds That Could Moderate Deployment Pace in Warehouse Robotics Market
- Capital cost sensitivity: Sustained higher interest rates extend payback periods, particularly for mid-market operators without scale economics.
- Integration risk: Failed deployments in early pilots have created procurement caution among enterprise buyers who watched peers stall.
- Standards fragmentation: Lack of interoperability between vendor fleets remains a real friction point for operators running mixed estates.
- Cybersecurity exposure: Connected fleets create attack surfaces that warehouse operations were not historically designed to defend.
- Talent scarcity at the operator level: The shortage of engineers who can run automated facilities is more binding than the shortage of robots.
- Regulatory uncertainty around labor displacement: Some jurisdictions are signaling policy responses that could affect deployment economics.
These headwinds will shape the pace of adoption but do not alter the directional conclusion. The operators absorbing these frictions early are building organizational muscle their slower competitors will need years to develop.
Market Dynamics Shaping the Warehouse Robotics Market
Warehouse Robotics Market Segmentation
By Product Type
- Autonomous Mobile Robots (AMR)
- Automated Guided Vehicles (AGV)
- Goods-To-Person Robots (GTP)
- Picking Systems
- Palletizers and Depalletizers
- Autonomous Forklift Robots
- Shuttle Robots and Shuttle Systems
- Sorting Robots
- Collaborative Robots (Cobots)
- Others
AMRs are absorbing the largest share of incremental deployment budgets because they offer the flexibility that fixed-path AGVs cannot match in environments where SKU mix and layout requirements evolve quarter to quarter. Goods-to-person systems remain the throughput backbone of high-volume e-commerce operations. Cobots are quietly expanding their footprint in mixed-task environments where full automation is uneconomic. Sorting robots are emerging as a critical sub-segment as parcel volumes continue to outpace conveyor-based capacity.
By Payload Capacity
- Ultra Light Payload (≤ 5 Kg)
- Light Payload (5–30 Kg)
- Medium Payload (30–100 Kg)
- Heavy Payload (Above 100 Kg)
Light payload systems dominate by unit volume because they map cleanly onto the dominant e-commerce parcel profile. Medium payload robots are the fastest-growing tier as 3PL operators expand into mixed industrial and consumer goods handling. Heavy payload automation remains concentrated in automotive, metals, and beverage operations where unit economics justify specialized equipment. The ultra-light category is being reshaped by collaborative picking arms in pharmaceutical and electronics environments.
By Application
- Order Picking
- Product Handling
- Palletizing and Depalletizing
- Conveying and Sortation
- Transportation
- Replenishment and Put-To-Light Operations
- Packing, Cartoning and Pallet Wrapping
- Quality Inspection
- Others
Order picking is the application where automation economics have improved most dramatically and where the largest enterprise budgets are flowing. Transportation within facilities, historically dominated by manual forklifts, is being reshaped by autonomous forklift adoption. Sortation is at an inflection driven by parcel volume growth. Quality inspection is emerging as a higher-margin application as vision systems mature and food and pharmaceutical operators face tighter compliance requirements.
By End Use
- E-Commerce and Retail
- Third-Party Logistics
- Food and Beverage
- Electronics and Electrical
- Metal and Machinery
- Automotive
- Pharmaceuticals
- Independent Warehouse
- Chemical, Rubber and Plastics
- Others
E-commerce and 3PL operators together account for the largest share of new deployment spending and set the pace of vendor innovation. Food and beverage is a structurally underpenetrated segment now accelerating as cold chain operators face acute labor pressure. Pharmaceutical automation is moving from compliance-driven pilots to throughput-driven scale deployment. Independent warehouse operators are entering the market through as-a-service contracts that did not exist as viable offerings three years ago.
Shape this report around your priorities: https://marketmindsadvisory.com/request-customization/?report_id=46
Regional Market Outlook
Investment Focus where Prominent Value Opportunity is Concentrating
Orchestration software and multi-vendor fleet management
The hardware margin compression underway across Asian manufacturing is structural. The defensible value is moving upstream to the software layer that coordinates heterogeneous fleets, integrates with warehouse execution systems, and provides the operational intelligence enterprise operators actually pay premium prices for. This is where the most attractive return profiles are concentrating.
Robotics-as-a-service Opportunities
The mid-market segment represents the largest unaddressed opportunity in the industry, and capex-based models have historically excluded it. Operators offering financed deployment, performance-based contracts, and managed fleet services are capturing customers competitors cannot economically reach. Recurring revenue economics also command structurally better valuations than hardware-only positions.
Vertical specialization in cold chain and pharmaceuticals
Cold chain, pharmaceutical, and regulated industry automation remains structurally underpenetrated relative to general merchandise. The compliance and operational requirements create defensible moats that broad-market vendors cannot easily replicate, and the customer economics support premium pricing that mass-market e-commerce automation does not.
AI-enabled perception and adaptive manipulation
Vendors with proprietary training data from years of pilot deployment now hold compounding advantages in adaptive picking capability. As more categories become automation-addressable, the perception layer becomes the gating capability. Companies that built data assets early are structurally advantaged against newer entrants attempting to catch up from zero.
What This Means for Decision-Makers
Warehouse Operators - Automation has crossed from competitive advantage into operational baseline. Securing integrator engagements and software partnerships through 2027 is the more decisive action than equipment selection. Operators delaying commitment are negotiating against peers who have already booked the scarce execution capacity.
Robotics Vendors - Hardware-only positioning is structurally weakening. The defensible competitive position is moving toward orchestration software, fleet management, and managed service models. Vendors without a credible software strategy face margin compression that scale alone cannot offset over the next deployment cycle.
Investors - The investment thesis has matured past pure hardware speculation. Software orchestration, as-a-service platforms, and vertically specialized vendors in regulated industries represent more attractive risk-return positions than general-purpose hardware bets that face Asian manufacturing pressure.
3PL and E-Commerce Strategy Teams - Treating robotics as a strategic asset rather than a procurement step is now the defining posture. The gap between operators who built early operational muscle and those still piloting is widening with each peak cycle, and that gap converts directly into cost structure and service capability.
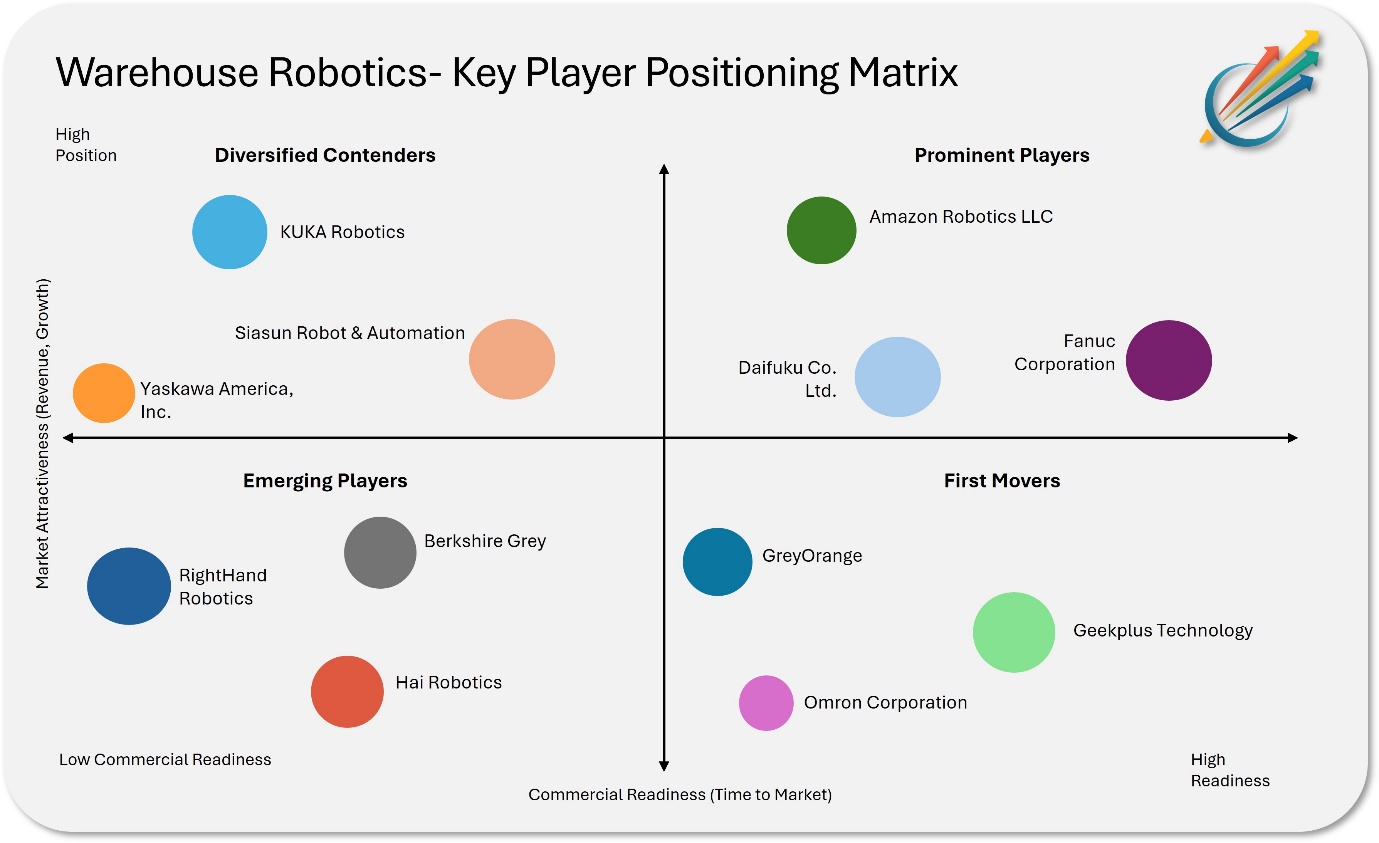
Competitive Landscape – Warehouse Robotics Market
Recent Market Developments
- In March 2026, Locus Robotics expanded its enterprise partnership footprint with additional 3PL operators deploying AMR fleets across North American distribution networks.
- In February 2026, Geekplus Technology announced expanded manufacturing capacity to address rising demand from European and Southeast Asian fulfillment operators.
- In January 2026, Kion Group reinforced its automation portfolio integration across its Dematic and Linde Material Handling business units to strengthen end-to-end warehouse solutions.
- In December 2025, ABB Robotics introduced expanded autonomous mobile robot capabilities targeting flexible manufacturing and warehouse logistics applications.
Market is segmented by Product Type (AMR, AGV, Goods-To-Person Robots, Picking Systems, Palletizers, Autonomous Forklifts, etc), Payload Capacity (Ultra Light, Light, Medium, Heavy), Application (Order Picking, Product Handling, Palletizing, Conveying and Sortation, Transportation, etc), and End Use (E-Commerce & Retail, 3PL, Food and Beverage, Electronics, Automotive, etc)
Get Access to complete Analysis, Buy Now: https://marketmindsadvisory.com/buy-now/?report_id=46
Trending Reports
- Packaging Automation Market
- Conveyors and Belt Loaders Market
- Industrial Security System Market
- Machine Condition Monitoring Market
- Automated Parcel Delivery Terminals Market
- Hyperlocal Food Delivery Market
- Collaborative Robots (Cobots) Market
- Dispensing Robots Market
- Pool-Cleaning Robots Market
- Military Robots Market
Why choose Market Minds Advisory
Market Minds Advisory delivers decision-grade intelligence to executives across machinery, packaging, chemicals, automotive, ICT, food and beverage, consumer goods, and healthcare. We help organizations sharpen market expansion strategies, accelerate share gains, refine brand positioning, and enable account-level growth. Our forecasting integrates primary interviews, proprietary demand models, and continuous market validation, producing the kind of clarity volatile and emerging industries require. Backed by over a decade of sector expertise, our research surfaces white space, opportunity gaps, and competitive blind spots, accounting for recent developments and geopolitical risk. We help businesses see the future of their markets.
Contact Us
Market Minds Advisory
1521 Concord Pike, Suite 301
Wilmington, DE 19803
United States
Email: sales@marketmindsadvisory.com
Website: https://marketmindsadvisory.com/
